The San Diego Blog
Stay up to date with what's going on locally
The San Diego Blog
Stay up to date with what's going on locally
Blogs
Stay up to date with everything going on
San Diego Blogs
Waiting for Lower Mortgage Rates? You Might Be Waiting Yourself Into a More Expensive Home!
Waiting for Lower Mortgage Rates?
You Might Be Waiting Yourself Into
a More Expensive San Diego Home! 🏡
I hear it all the time from homebuyers:
"We're going to wait until mortgage rates come down."
Fair enough. Nobody wants to pay more interest than necessary. But here's something I've learned over my 27 years in real estate:
A lower interest rate doesn't necessarily mean a less expensive home.
Sometimes, waiting for a lower rate actually costs you MORE.
Let's Do Some San Diego Math!
Take a hypothetical home in Clairemont, ZIP code 92117, where median sale prices increased 6.6% year-over-year through September 2026, according to Redfin.
Let's compare buying today versus waiting another year.
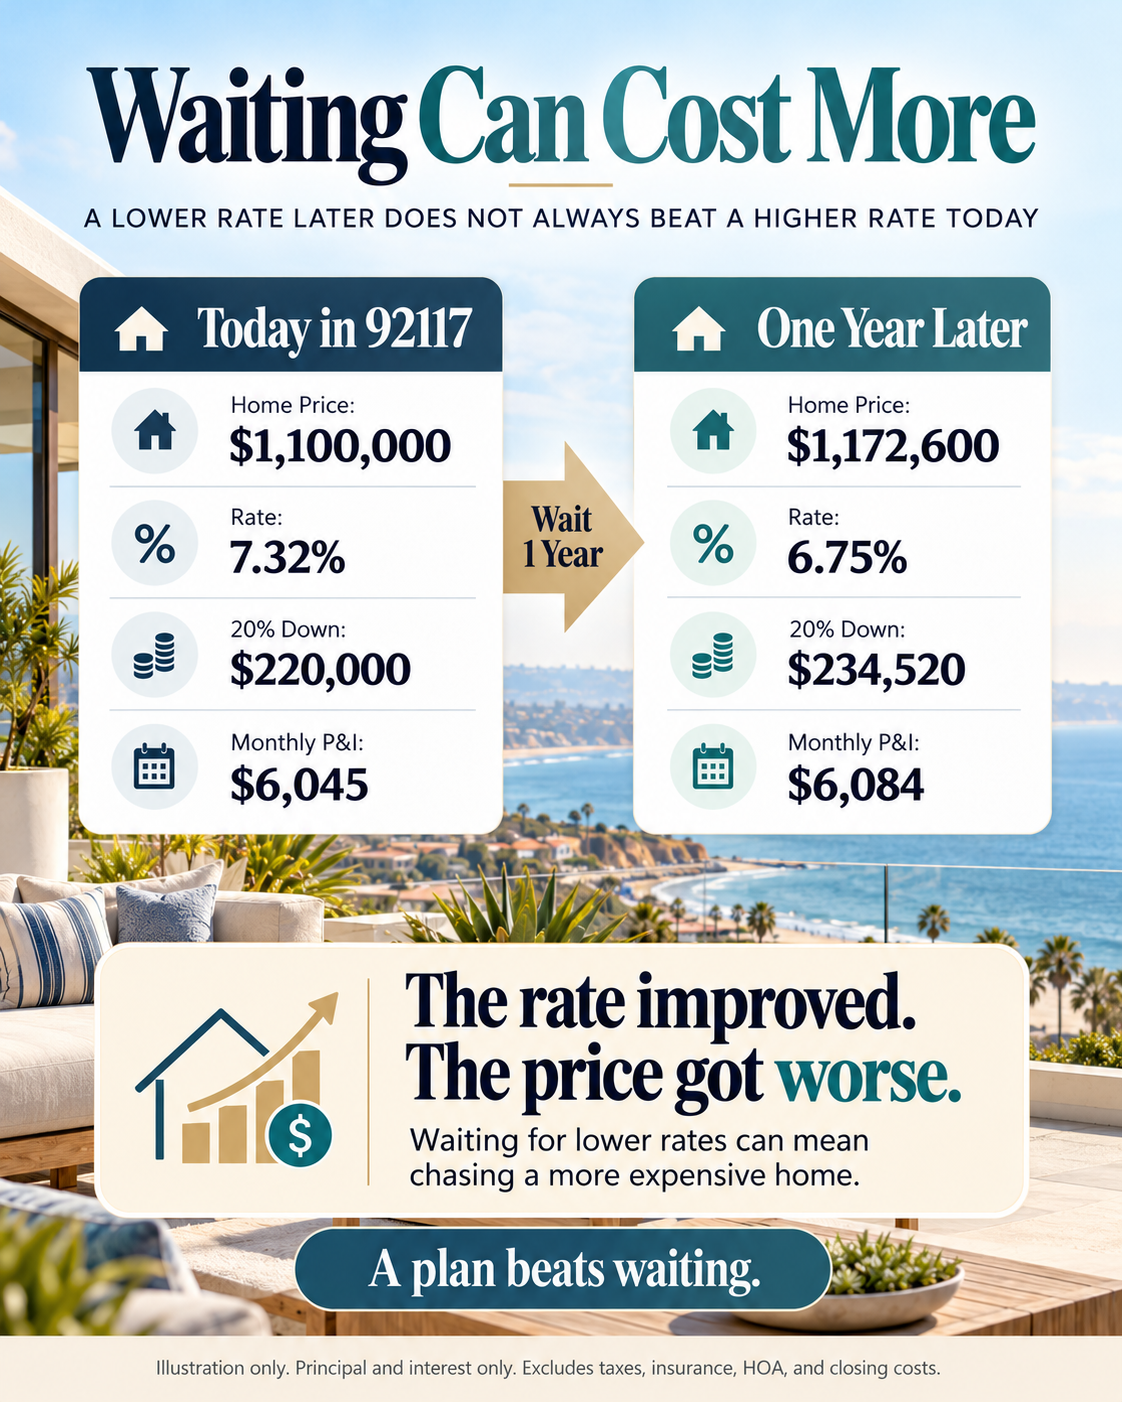
Scenario 1: Buy Today
Purchase price: $1,100,000
Down payment (20%): $220,000
Mortgage rate: 7.32%
Monthly principal and interest: $6,045
Scenario 2: Wait One Year
Suppose that home appreciates 6.6% while mortgage rates decline.
Purchase price: $1,172,600
Down payment (20%): $234,520
Mortgage rate: 6.75%
Monthly principal and interest: $6,084
WAIT! The interest rate dropped, but the buyer now needs $14,520 MORE for the down payment and has a HIGHER monthly mortgage payment!
And here's what many buyers overlook.
The person who bought earlier could potentially refinance that smaller mortgage at 6.75%, reducing their monthly principal and interest to approximately $5,714 over the remaining 29 years, before refinancing costs.
Same neighborhood. Lower loan balance. Better position.
When you own a home, rising property values can build YOUR equity instead of increasing the price of a home you're still trying to buy!
My Advice?
I'm not suggesting home prices always rise, rates always fall, or everyone should rush into buying. They don't, and they shouldn't.
I'm suggesting we stop trying to predict the perfect market and start developing smarter financial strategies.
As your REALTOR®, my job isn't to sell you a mortgage payment. It's to help you make an informed decision and develop a plan that fits your financial goals.
Because waiting might save you money. But having a PLAN puts you in control! 🏡
Illustrations assume a 30-year fixed-rate mortgage, exclude taxes, insurance, HOA fees and transaction costs, and do not guarantee future appreciation or refinancing availability.
Interviews
Waiting for Lower Mortgage Rates? You Might Be Waiting Yourself Into a More Expensive Home!
Waiting for Lower Mortgage Rates?
You Might Be Waiting Yourself Into
a More Expensive San Diego Home! 🏡
I hear it all the time from homebuyers:
"We're going to wait until mortgage rates come down."
Fair enough. Nobody wants to pay more interest than necessary. But here's something I've learned over my 27 years in real estate:
A lower interest rate doesn't necessarily mean a less expensive home.
Sometimes, waiting for a lower rate actually costs you MORE.
Let's Do Some San Diego Math!
Take a hypothetical home in Clairemont, ZIP code 92117, where median sale prices increased 6.6% year-over-year through September 2026, according to Redfin.
Let's compare buying today versus waiting another year.
Scenario 1: Buy Today
Purchase price: $1,100,000
Down payment (20%): $220,000
Mortgage rate: 7.32%
Monthly principal and interest: $6,045
Scenario 2: Wait One Year
Suppose that home appreciates 6.6% while mortgage rates decline.
Purchase price: $1,172,600
Down payment (20%): $234,520
Mortgage rate: 6.75%
Monthly principal and interest: $6,084
WAIT! The interest rate dropped, but the buyer now needs $14,520 MORE for the down payment and has a HIGHER monthly mortgage payment!
And here's what many buyers overlook.
The person who bought earlier could potentially refinance that smaller mortgage at 6.75%, reducing their monthly principal and interest to approximately $5,714 over the remaining 29 years, before refinancing costs.
Same neighborhood. Lower loan balance. Better position.
When you own a home, rising property values can build YOUR equity instead of increasing the price of a home you're still trying to buy!
My Advice?
I'm not suggesting home prices always rise, rates always fall, or everyone should rush into buying. They don't, and they shouldn't.
I'm suggesting we stop trying to predict the perfect market and start developing smarter financial strategies.
As your REALTOR®, my job isn't to sell you a mortgage payment. It's to help you make an informed decision and develop a plan that fits your financial goals.
Because waiting might save you money. But having a PLAN puts you in control! 🏡
Illustrations assume a 30-year fixed-rate mortgage, exclude taxes, insurance, HOA fees and transaction costs, and do not guarantee future appreciation or refinancing availability.
Articles
Waiting for Lower Mortgage Rates? You Might Be Waiting Yourself Into a More Expensive Home!
Waiting for Lower Mortgage Rates?
You Might Be Waiting Yourself Into
a More Expensive San Diego Home! 🏡
I hear it all the time from homebuyers:
"We're going to wait until mortgage rates come down."
Fair enough. Nobody wants to pay more interest than necessary. But here's something I've learned over my 27 years in real estate:
A lower interest rate doesn't necessarily mean a less expensive home.
Sometimes, waiting for a lower rate actually costs you MORE.
Let's Do Some San Diego Math!
Take a hypothetical home in Clairemont, ZIP code 92117, where median sale prices increased 6.6% year-over-year through September 2026, according to Redfin.
Let's compare buying today versus waiting another year.
Scenario 1: Buy Today
Purchase price: $1,100,000
Down payment (20%): $220,000
Mortgage rate: 7.32%
Monthly principal and interest: $6,045
Scenario 2: Wait One Year
Suppose that home appreciates 6.6% while mortgage rates decline.
Purchase price: $1,172,600
Down payment (20%): $234,520
Mortgage rate: 6.75%
Monthly principal and interest: $6,084
WAIT! The interest rate dropped, but the buyer now needs $14,520 MORE for the down payment and has a HIGHER monthly mortgage payment!
And here's what many buyers overlook.
The person who bought earlier could potentially refinance that smaller mortgage at 6.75%, reducing their monthly principal and interest to approximately $5,714 over the remaining 29 years, before refinancing costs.
Same neighborhood. Lower loan balance. Better position.
When you own a home, rising property values can build YOUR equity instead of increasing the price of a home you're still trying to buy!
My Advice?
I'm not suggesting home prices always rise, rates always fall, or everyone should rush into buying. They don't, and they shouldn't.
I'm suggesting we stop trying to predict the perfect market and start developing smarter financial strategies.
As your REALTOR®, my job isn't to sell you a mortgage payment. It's to help you make an informed decision and develop a plan that fits your financial goals.
Because waiting might save you money. But having a PLAN puts you in control! 🏡
Illustrations assume a 30-year fixed-rate mortgage, exclude taxes, insurance, HOA fees and transaction costs, and do not guarantee future appreciation or refinancing availability.
#58BB47
#0000FF
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph
Thank you for visiting
San Diego
Contact Info
Address
8895 Towne Centre Dr. Ste 105 PMB 436, San Diego, CA 92122-5542
Phone
+18582328722
Location
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph