There's So Much Happening Here
Welcome to
San Diego Neighborhood Experts
There's So Much Happening Here...
LOCAL AMBASSADOR
Thomas J. Nelson
Welcome, my friends, to San Diego Neighborhood Experts, your one-stop shop for all things local! Here, we bring you exclusive interviews with our beloved neighborhood businesses, the latest happenings in San Diego, fresh events to look out for, and of course, juicy tidbits about the ever-exciting real estate market. Stay classy, San Diego!
My mission is to inspire growth and cultivate financial freedom by delivering exceptional real estate services. As a perpetual learner and explorer, I serve others with energy and focus, using pragmatic communication and a global perspective to create deep connections and make a meaningful impact. A treasure hunter at heart, I embrace every opportunity to motivate and empower those I serve and achieve success in all our ventures.


San Diego Neighborhood Experts Podcast
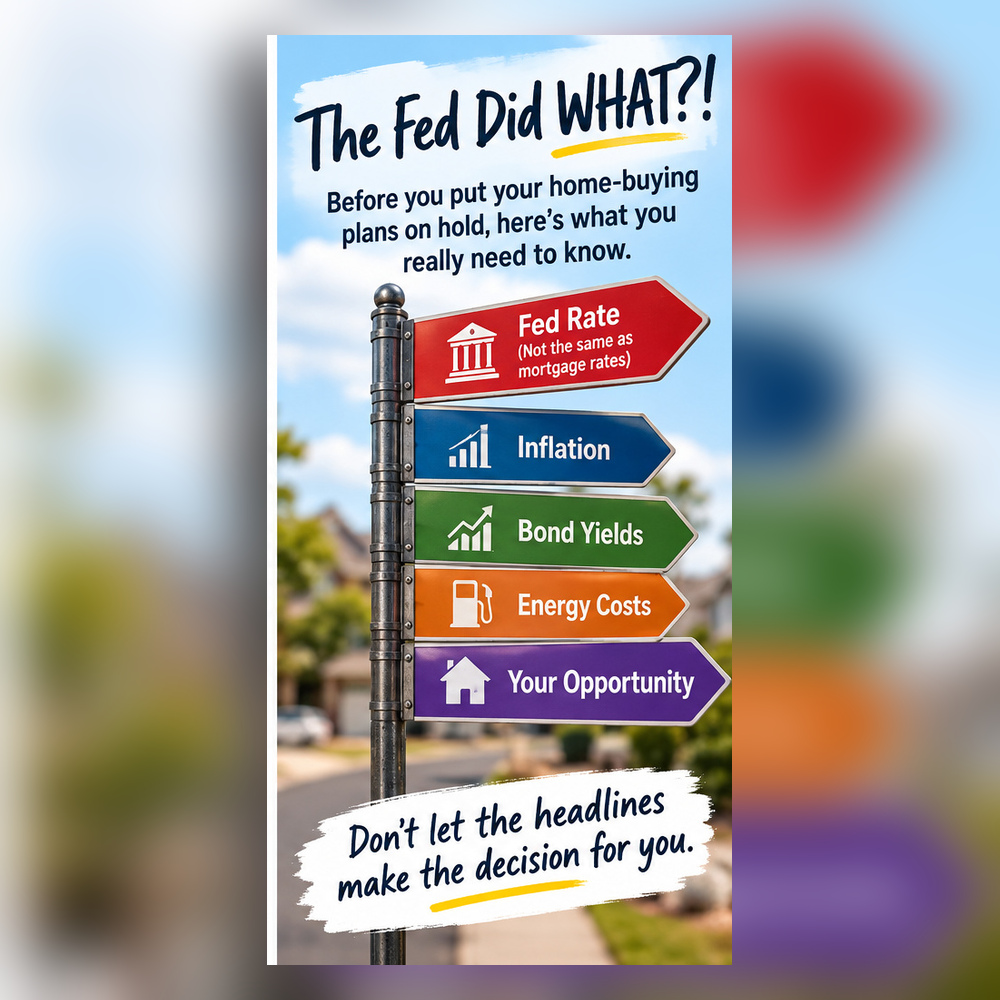
Waiting for Mortgage Rates to Drop? You Might Want a Chair.
Waiting for Mortgage Rates to Drop?
You Might Want a Chair.
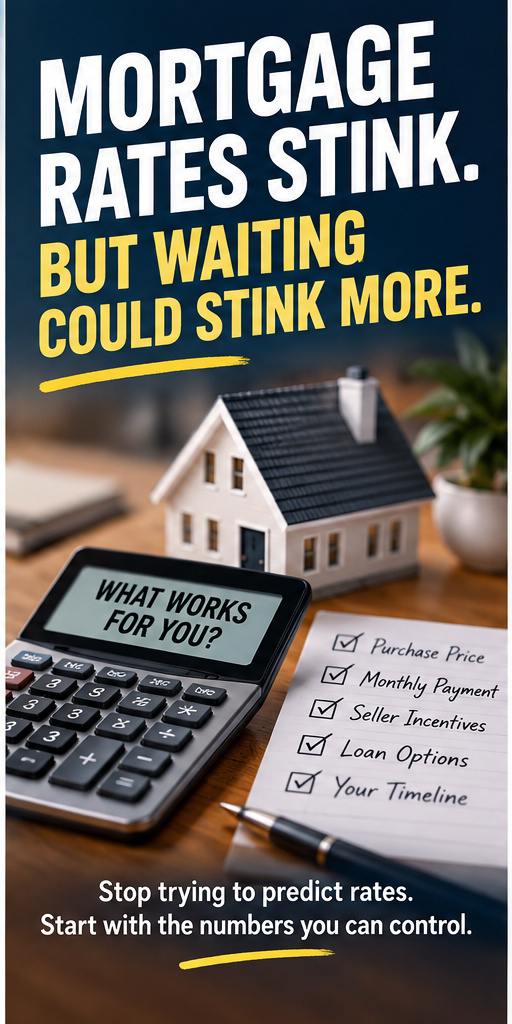
Let’s just say it: mortgage rates are painful right now.
And whenever rates spike, the predictable advice starts flying around: “Wait until rates come down.”
Maybe. But before you put your home-buying plans on ice, understand something important:
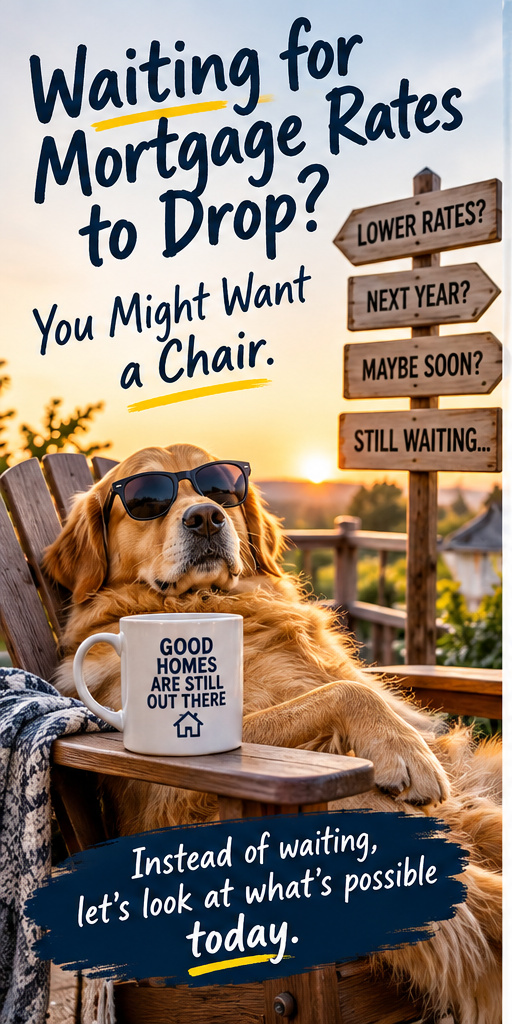
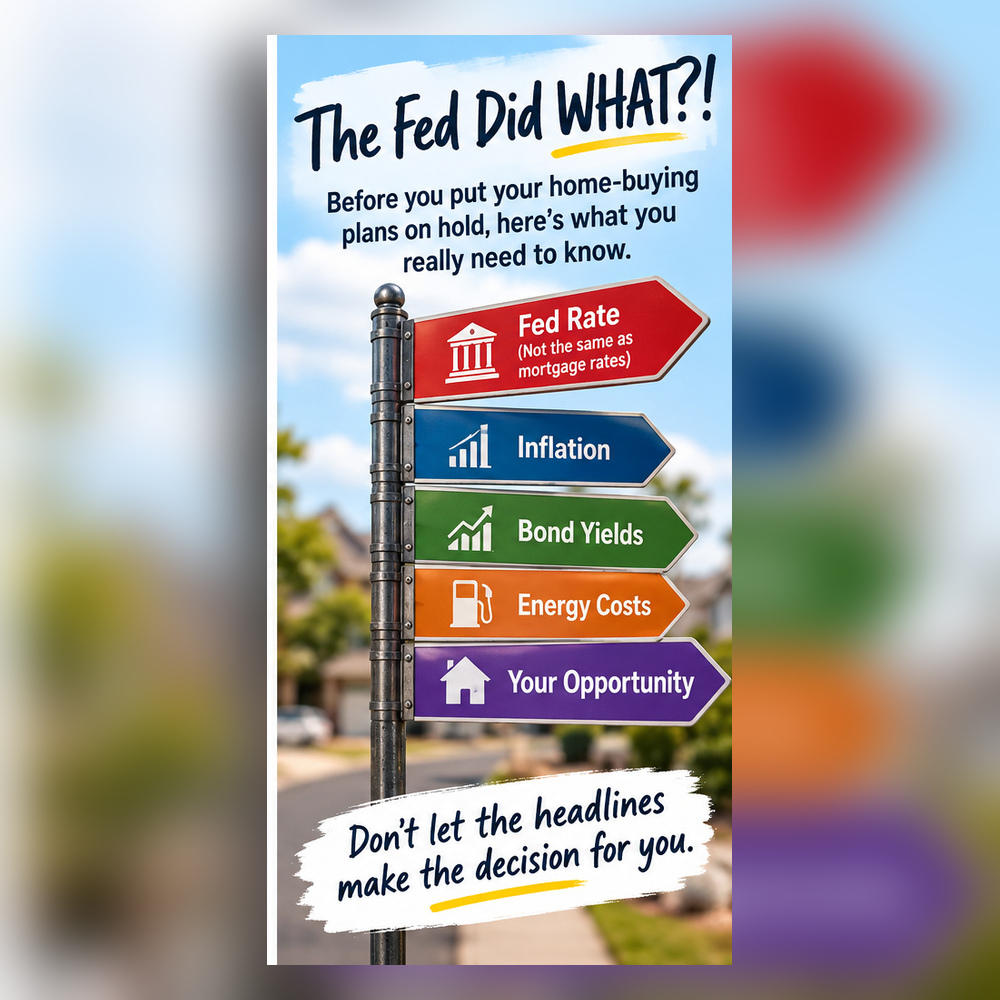
The Federal Reserve does NOT directly set mortgage rates.
The Fed controls the federal funds rate—the overnight rate banks charge one another. Mortgage rates are influenced by a much larger economic stew: inflation, Treasury and bond yields, government borrowing, energy costs, investor expectations and the overall economy.
That’s why mortgage rates can rise, fall or start moving before the Fed does anything.
Stop Trying to Time Rates.
Start With Your Payment.
Nobody—not your REALTOR®, lender, economist, financial-news talking head, or your neighbor who “almost became a REALTOR®”—knows exactly where mortgage rates will be six months from now.
So I think buyers should ask
a better question:
“What would have to happen for buying a home to make sense for me TODAY?”
Start with the monthly payment you’re genuinely comfortable making—not simply the maximum amount somebody says you qualify for.
Then determine the gap.
If the house you want puts you $200 or $300 above that comfort zone, can we bridge it?
Possibly.
A negotiated purchase price, seller credit, interest-rate buydown, improved credit, paying down another debt, or a different loan program might change the equation. Adjustable-rate mortgages (ARMs) are also getting another look from some buyers, although you need to clearly understand when and how that rate can adjust.
And today’s slower market may actually create opportunities for buyers to negotiate terms that were much harder to get when everyone was fighting over the same house.
Sometimes Waiting IS the Right Answer
If buying today would wipe out your savings,
make you house-poor, or leave you
uncomfortable every month, wait.
That’s a financial decision based on facts.
But “I’m waiting because rates will be lower next year” is a prediction—and nobody knows that.
Rates could decline. They could remain elevated. Home prices could move. Inventory could tighten. The perfect house could appear—or disappear.
You don’t need to buy today. But you should know what buying today actually looks like before deciding not to.
Forget the headlines for a minute.
Let’s find the house, run the numbers, understand the options, and then decide whether they make sense for you.
Need the Financing Side of the Conversation?
I recommend my lending partner Jason Gordon at CrossCountry Mortgage. Jason can help you understand the actual financing options and numbers instead of trying to make decisions from national headlines.
Jason Gordon
Sr. Loan Consultant / Advisor
CrossCountry Mortgage, LLC
📱 619.200.8031 | Direct: 760.268.9830
✉️ [email protected]
Jason Gordon — CrossCountry Mortgage
805 College Blvd., Suite 103
Oceanside, CA 92057
Personal NMLS 259027 | Branch NMLS 2779573 | Company NMLS 3029

Waiting for Mortgage Rates to Drop? You Might Want a Chair.
Waiting for Mortgage Rates to Drop?
You Might Want a Chair.
Let’s just say it: mortgage rates are painful right now.
And whenever rates spike, the predictable advice starts flying around: “Wait until rates come down.”
Maybe. But before you put your home-buying plans on ice, understand something important:
The Federal Reserve does NOT directly set mortgage rates.
The Fed controls the federal funds rate—the overnight rate banks charge one another. Mortgage rates are influenced by a much larger economic stew: inflation, Treasury and bond yields, government borrowing, energy costs, investor expectations and the overall economy.
That’s why mortgage rates can rise, fall or start moving before the Fed does anything.
Stop Trying to Time Rates.
Start With Your Payment.
Nobody—not your REALTOR®, lender, economist, financial-news talking head, or your neighbor who “almost became a REALTOR®”—knows exactly where mortgage rates will be six months from now.
So I think buyers should ask
a better question:
“What would have to happen for buying a home to make sense for me TODAY?”
Start with the monthly payment you’re genuinely comfortable making—not simply the maximum amount somebody says you qualify for.
Then determine the gap.
If the house you want puts you $200 or $300 above that comfort zone, can we bridge it?
Possibly.
A negotiated purchase price, seller credit, interest-rate buydown, improved credit, paying down another debt, or a different loan program might change the equation. Adjustable-rate mortgages (ARMs) are also getting another look from some buyers, although you need to clearly understand when and how that rate can adjust.
And today’s slower market may actually create opportunities for buyers to negotiate terms that were much harder to get when everyone was fighting over the same house.
Sometimes Waiting IS the Right Answer
If buying today would wipe out your savings,
make you house-poor, or leave you
uncomfortable every month, wait.
That’s a financial decision based on facts.
But “I’m waiting because rates will be lower next year” is a prediction—and nobody knows that.
Rates could decline. They could remain elevated. Home prices could move. Inventory could tighten. The perfect house could appear—or disappear.
You don’t need to buy today. But you should know what buying today actually looks like before deciding not to.
Forget the headlines for a minute.
Let’s find the house, run the numbers, understand the options, and then decide whether they make sense for you.
Need the Financing Side of the Conversation?
I recommend my lending partner Jason Gordon at CrossCountry Mortgage. Jason can help you understand the actual financing options and numbers instead of trying to make decisions from national headlines.
Jason Gordon
Sr. Loan Consultant / Advisor
CrossCountry Mortgage, LLC
📱 619.200.8031 | Direct: 760.268.9830
✉️ [email protected]
Jason Gordon — CrossCountry Mortgage
805 College Blvd., Suite 103
Oceanside, CA 92057
Personal NMLS 259027 | Branch NMLS 2779573 | Company NMLS 3029
San Diego Neighborhood Experts is a FREE community initiative to help locals get to know each other and encourage everyone to shop local!
Apply to have your business interviewed and featured on the podcast for free!
San Diego Blogs
Waiting for Mortgage Rates to Drop? You Might Want a Chair.
Waiting for Mortgage Rates to Drop?
You Might Want a Chair.
Let’s just say it: mortgage rates are painful right now.
And whenever rates spike, the predictable advice starts flying around: “Wait until rates come down.”
Maybe. But before you put your home-buying plans on ice, understand something important:
The Federal Reserve does NOT directly set mortgage rates.
The Fed controls the federal funds rate—the overnight rate banks charge one another. Mortgage rates are influenced by a much larger economic stew: inflation, Treasury and bond yields, government borrowing, energy costs, investor expectations and the overall economy.
That’s why mortgage rates can rise, fall or start moving before the Fed does anything.
Stop Trying to Time Rates.
Start With Your Payment.
Nobody—not your REALTOR®, lender, economist, financial-news talking head, or your neighbor who “almost became a REALTOR®”—knows exactly where mortgage rates will be six months from now.
So I think buyers should ask
a better question:
“What would have to happen for buying a home to make sense for me TODAY?”
Start with the monthly payment you’re genuinely comfortable making—not simply the maximum amount somebody says you qualify for.
Then determine the gap.
If the house you want puts you $200 or $300 above that comfort zone, can we bridge it?
Possibly.
A negotiated purchase price, seller credit, interest-rate buydown, improved credit, paying down another debt, or a different loan program might change the equation. Adjustable-rate mortgages (ARMs) are also getting another look from some buyers, although you need to clearly understand when and how that rate can adjust.
And today’s slower market may actually create opportunities for buyers to negotiate terms that were much harder to get when everyone was fighting over the same house.
Sometimes Waiting IS the Right Answer
If buying today would wipe out your savings,
make you house-poor, or leave you
uncomfortable every month, wait.
That’s a financial decision based on facts.
But “I’m waiting because rates will be lower next year” is a prediction—and nobody knows that.
Rates could decline. They could remain elevated. Home prices could move. Inventory could tighten. The perfect house could appear—or disappear.
You don’t need to buy today. But you should know what buying today actually looks like before deciding not to.
Forget the headlines for a minute.
Let’s find the house, run the numbers, understand the options, and then decide whether they make sense for you.
Need the Financing Side of the Conversation?
I recommend my lending partner Jason Gordon at CrossCountry Mortgage. Jason can help you understand the actual financing options and numbers instead of trying to make decisions from national headlines.
Jason Gordon
Sr. Loan Consultant / Advisor
CrossCountry Mortgage, LLC
📱 619.200.8031 | Direct: 760.268.9830
✉️ [email protected]
Jason Gordon — CrossCountry Mortgage
805 College Blvd., Suite 103
Oceanside, CA 92057
Personal NMLS 259027 | Branch NMLS 2779573 | Company NMLS 3029
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/65ed25120013ad8189925cc4.jpeg
#58BB47
#0000FF
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/663e5366699c7e1eb628841a.jpeg
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph
Thank you for visiting
San Diego
Contact Info
Address
8895 Towne Centre Dr. Ste 105 PMB 436, San Diego, CA 92122-5542
Phone
+18582328722
Location
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph