There's So Much Happening Here
Welcome to
San Diego Neighborhood Experts
There's So Much Happening Here...
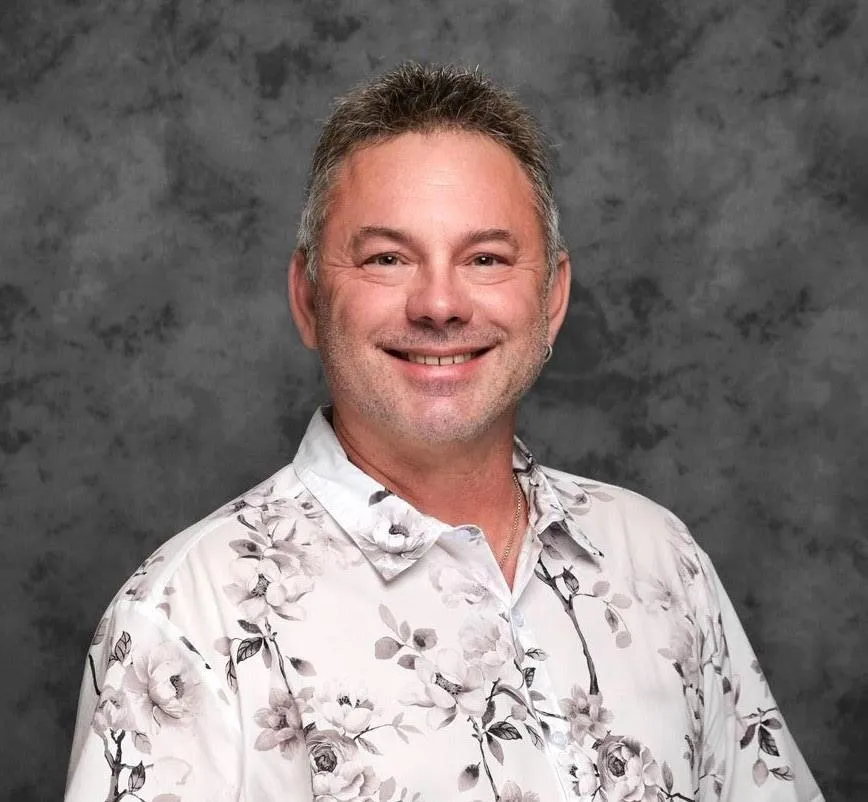
LOCAL AMBASSADOR
Thomas J. Nelson
Welcome, my friends, to San Diego Neighborhood Experts, your one-stop shop for all things local! Here, we bring you exclusive interviews with our beloved neighborhood businesses, the latest happenings in San Diego, fresh events to look out for, and of course, juicy tidbits about the ever-exciting real estate market. Stay classy, San Diego!
My mission is to inspire growth and cultivate financial freedom by delivering exceptional real estate services. As a perpetual learner and explorer, I serve others with energy and focus, using pragmatic communication and a global perspective to create deep connections and make a meaningful impact. A treasure hunter at heart, I embrace every opportunity to motivate and empower those I serve and achieve success in all our ventures.


San Diego Neighborhood Experts Podcast
San Diego Home Sales & Mortgage Rates: Oct 2026 Insights & Answers
Real Estate, Home Sales, Mortgage Rates, San Diego
San Diego Home Sales & Mortgage Rates: What Buyers and Sellers Should Know in October 2026
If you’re thinking about buying or selling a home in San Diego, CA in October 2026, you’re stepping into a market that’s cooling in pace but still expensive, with mortgage rates hovering near multi‑year highs. Here’s a clear, data‑driven look at what’s happening with home sales and mortgage rates—and what it means for your next move.
San Diego Housing Market, October 2026
High rates, shifting demand, and new opportunities for buyers and sellers
Home Sales in San Diego: Slower Pace, Split Story by Property Type
Because full October 2026 numbers aren’t released yet, September data provides the best snapshot of where the San Diego market stands right now. Countywide, the median sales price for all homes (detached and attached) was about $910,000, up roughly 1.7% from September 2025, according to local MLS-based reports cited by Dawn Sells San Diego and SnapDwell (dawnsellssandiego.com, snapdwell.com). At the same time, closed sales dropped about 14% year over year, signaling fewer completed transactions and more cautious buyers.
The story changes when you separate single‑family homes from condos and townhomes:
Detached homes (single‑family): Median sale price around $1,079,000, up 5.8% year over year. Inventory is tighter, and these homes are selling faster—about 37 days on market, nearly 10% quicker than last year. Closed and pending sales are both down double digits, but sellers still have the upper hand due to limited supply (loveryrealestate.com).
Attached homes (condos & townhomes): Median price around $670,000, essentially flat—down about 0.2% year over year. Inventory here has grown roughly 5–6%, days on market have stretched to about 44 days, and sales are off about 14%, pointing to a softer, more buyer‑friendly segment.
Early October “rolling 30‑day” data (through mid‑October) shows the median sold price dipping slightly to around $915,000, with homes taking about 51 days to sell and a market score leaning toward buyers (about 33 out of 100 on a buyer–seller scale), according to PocketAgentPro. That suggests the market is no longer the frenzied seller’s arena of 2021–2022, even if prices remain high.

Slower sales mean buyers can negotiate more, especially on condos and townhomes.
Mortgage Rates in October 2026: High, but Shop Around
The biggest headwind in San Diego right now is borrowing costs. As of mid‑to‑late October 2026, most 30‑year fixed mortgage rates in the area sit between 7.3% and 7.5%, very close to the national average of about 7.4% reported by Freddie Mac (monitorbankrates.com, apnews.com). Some local lenders and credit unions do stand out: Safe 1 Credit Union, for example, has recently advertised a 30‑year fixed rate near 6.00% (about 6.085% APR), which is significantly lower than many big‑bank offers.
On the higher end, jumbo and specialty loans can climb above 9%, especially for borrowers with lower credit scores or smaller down payments. That spread—from roughly 6% to the high‑8s/9s—means your personal rate will depend heavily on your credit profile, loan size, and loan‑to‑value ratio, not just where you apply.
💡 Pro Tip: When comparing offers, focus on APR, not just the headline rate. APR factors in lender fees and can reveal which loan is truly cheaper over time.
What This Means for San Diego Buyers in October 2026
For buyers, this fall is a trade‑off: more negotiating room and slightly better selection, especially in condos and townhomes, but at the cost of higher monthly payments due to rates in the 7–8% range. Realtor.com and Axios both highlight mid‑October—specifically the week of October 11–17—as one of the best times of year to buy in San Diego, with listing prices typically several percentage points below seasonal peaks and more active inventory on the market (axios.com).
If you’re determined to purchase in 2026, consider:
Focusing on attached homes where prices are flatter and sellers are more flexible.
Getting quotes from multiple lenders and credit unions—the difference between 6.0% and 7.5% can mean hundreds of dollars per month.
Planning a potential refinance in the future if rates ease, while making sure the payment you lock in today is still comfortable.
Guidance for Sellers: Strategy Matters More Than Ever
Sellers of detached homes in San Diego are still in a relatively strong position: prices are up 5–6% year over year, inventory is tight, and well‑priced homes can move in just over a month. However, the pool of qualified buyers has shrunk as rates climbed, so overpricing is more likely to backfire than in past years. For condo and townhome sellers, where inventory is higher and days on market are longer, realistic pricing, strong staging, and small concessions (like closing cost credits or rate‑buydown contributions) can make the difference between lingering and selling.
Overall, October 2026 in San Diego is a market in transition: home sales are slower, mortgage rates are elevated, and leverage is shifting slightly toward buyers—especially in the attached segment—while detached homes remain resilient. Whether you’re buying or selling, grounding your decisions in current data and carefully comparing mortgage options will help you navigate this moment with confidence.
A Little More Perspective on Today's Housing Market
Sandra, I've included three short videos that help explain some of the economic factors influencing today's real estate market. My intention isn't to overwhelm you with news, but to provide some helpful perspective on why the market is changing and what that means for buyers and sellers.
1. Housing Affordability — Why Buyers Are Being Priced Out
Watch Video: Housing Market Trends & Affordability
An overview of the affordability challenges facing today's homebuyers, including how the rising costs of homeownership are limiting the number of people able to purchase a home.
2. Why Home Sales Are Slowing
Watch Video: What's Behind the Slowdown in Home Sales?
A look at how inflation, mortgage interest rates, and the rising cost of living are affecting buyers' purchasing power and contributing to slower home sales.
3. Mortgage Interest Rates — Why They Matter So Much
Watch Video: Understanding Mortgage Rates and Their Impact
A helpful explanation of how mortgage rates influence monthly payments, buying power, and ultimately what buyers can afford to pay for a home.
My Perspective
These broader market trends are important to understand, but real estate is ultimately local. Your home's value will depend on comparable sales in your neighborhood, its condition, and the buyers actively shopping in your price range.
My job is to help you separate the headlines from the realities of your particular market, so you can make decisions based on facts rather than fear or speculation. I will provide you with a FREE Equity Report on your home, all I need is your address, name & email. No sales pitches, no heavy follow up - just good info and answer to your questions. I works by referral, not sales pressure.😉~ Thomas J Nelson

San Diego Home Sales & Mortgage Rates: Oct 2026 Insights & Answers
Real Estate, Home Sales, Mortgage Rates, San Diego
San Diego Home Sales & Mortgage Rates: What Buyers and Sellers Should Know in October 2026
If you’re thinking about buying or selling a home in San Diego, CA in October 2026, you’re stepping into a market that’s cooling in pace but still expensive, with mortgage rates hovering near multi‑year highs. Here’s a clear, data‑driven look at what’s happening with home sales and mortgage rates—and what it means for your next move.
San Diego Housing Market, October 2026
High rates, shifting demand, and new opportunities for buyers and sellers
Home Sales in San Diego: Slower Pace, Split Story by Property Type
Because full October 2026 numbers aren’t released yet, September data provides the best snapshot of where the San Diego market stands right now. Countywide, the median sales price for all homes (detached and attached) was about $910,000, up roughly 1.7% from September 2025, according to local MLS-based reports cited by Dawn Sells San Diego and SnapDwell (dawnsellssandiego.com, snapdwell.com). At the same time, closed sales dropped about 14% year over year, signaling fewer completed transactions and more cautious buyers.
The story changes when you separate single‑family homes from condos and townhomes:
Detached homes (single‑family): Median sale price around $1,079,000, up 5.8% year over year. Inventory is tighter, and these homes are selling faster—about 37 days on market, nearly 10% quicker than last year. Closed and pending sales are both down double digits, but sellers still have the upper hand due to limited supply (loveryrealestate.com).
Attached homes (condos & townhomes): Median price around $670,000, essentially flat—down about 0.2% year over year. Inventory here has grown roughly 5–6%, days on market have stretched to about 44 days, and sales are off about 14%, pointing to a softer, more buyer‑friendly segment.
Early October “rolling 30‑day” data (through mid‑October) shows the median sold price dipping slightly to around $915,000, with homes taking about 51 days to sell and a market score leaning toward buyers (about 33 out of 100 on a buyer–seller scale), according to PocketAgentPro. That suggests the market is no longer the frenzied seller’s arena of 2021–2022, even if prices remain high.
Slower sales mean buyers can negotiate more, especially on condos and townhomes.
Mortgage Rates in October 2026: High, but Shop Around
The biggest headwind in San Diego right now is borrowing costs. As of mid‑to‑late October 2026, most 30‑year fixed mortgage rates in the area sit between 7.3% and 7.5%, very close to the national average of about 7.4% reported by Freddie Mac (monitorbankrates.com, apnews.com). Some local lenders and credit unions do stand out: Safe 1 Credit Union, for example, has recently advertised a 30‑year fixed rate near 6.00% (about 6.085% APR), which is significantly lower than many big‑bank offers.
On the higher end, jumbo and specialty loans can climb above 9%, especially for borrowers with lower credit scores or smaller down payments. That spread—from roughly 6% to the high‑8s/9s—means your personal rate will depend heavily on your credit profile, loan size, and loan‑to‑value ratio, not just where you apply.
💡 Pro Tip: When comparing offers, focus on APR, not just the headline rate. APR factors in lender fees and can reveal which loan is truly cheaper over time.
What This Means for San Diego Buyers in October 2026
For buyers, this fall is a trade‑off: more negotiating room and slightly better selection, especially in condos and townhomes, but at the cost of higher monthly payments due to rates in the 7–8% range. Realtor.com and Axios both highlight mid‑October—specifically the week of October 11–17—as one of the best times of year to buy in San Diego, with listing prices typically several percentage points below seasonal peaks and more active inventory on the market (axios.com).
If you’re determined to purchase in 2026, consider:
Focusing on attached homes where prices are flatter and sellers are more flexible.
Getting quotes from multiple lenders and credit unions—the difference between 6.0% and 7.5% can mean hundreds of dollars per month.
Planning a potential refinance in the future if rates ease, while making sure the payment you lock in today is still comfortable.
Guidance for Sellers: Strategy Matters More Than Ever
Sellers of detached homes in San Diego are still in a relatively strong position: prices are up 5–6% year over year, inventory is tight, and well‑priced homes can move in just over a month. However, the pool of qualified buyers has shrunk as rates climbed, so overpricing is more likely to backfire than in past years. For condo and townhome sellers, where inventory is higher and days on market are longer, realistic pricing, strong staging, and small concessions (like closing cost credits or rate‑buydown contributions) can make the difference between lingering and selling.
Overall, October 2026 in San Diego is a market in transition: home sales are slower, mortgage rates are elevated, and leverage is shifting slightly toward buyers—especially in the attached segment—while detached homes remain resilient. Whether you’re buying or selling, grounding your decisions in current data and carefully comparing mortgage options will help you navigate this moment with confidence.
A Little More Perspective on Today's Housing Market
Sandra, I've included three short videos that help explain some of the economic factors influencing today's real estate market. My intention isn't to overwhelm you with news, but to provide some helpful perspective on why the market is changing and what that means for buyers and sellers.
1. Housing Affordability — Why Buyers Are Being Priced Out
Watch Video: Housing Market Trends & Affordability
An overview of the affordability challenges facing today's homebuyers, including how the rising costs of homeownership are limiting the number of people able to purchase a home.
2. Why Home Sales Are Slowing
Watch Video: What's Behind the Slowdown in Home Sales?
A look at how inflation, mortgage interest rates, and the rising cost of living are affecting buyers' purchasing power and contributing to slower home sales.
3. Mortgage Interest Rates — Why They Matter So Much
Watch Video: Understanding Mortgage Rates and Their Impact
A helpful explanation of how mortgage rates influence monthly payments, buying power, and ultimately what buyers can afford to pay for a home.
My Perspective
These broader market trends are important to understand, but real estate is ultimately local. Your home's value will depend on comparable sales in your neighborhood, its condition, and the buyers actively shopping in your price range.
My job is to help you separate the headlines from the realities of your particular market, so you can make decisions based on facts rather than fear or speculation. I will provide you with a FREE Equity Report on your home, all I need is your address, name & email. No sales pitches, no heavy follow up - just good info and answer to your questions. I works by referral, not sales pressure.😉~ Thomas J Nelson
San Diego Neighborhood Experts is a FREE community initiative to help locals get to know each other and encourage everyone to shop local!
Apply to have your business interviewed and featured on the podcast for free!
San Diego Blogs
San Diego Home Sales & Mortgage Rates: Oct 2026 Insights & Answers
Real Estate, Home Sales, Mortgage Rates, San Diego
San Diego Home Sales & Mortgage Rates: What Buyers and Sellers Should Know in October 2026
If you’re thinking about buying or selling a home in San Diego, CA in October 2026, you’re stepping into a market that’s cooling in pace but still expensive, with mortgage rates hovering near multi‑year highs. Here’s a clear, data‑driven look at what’s happening with home sales and mortgage rates—and what it means for your next move.
San Diego Housing Market, October 2026
High rates, shifting demand, and new opportunities for buyers and sellers
Home Sales in San Diego: Slower Pace, Split Story by Property Type
Because full October 2026 numbers aren’t released yet, September data provides the best snapshot of where the San Diego market stands right now. Countywide, the median sales price for all homes (detached and attached) was about $910,000, up roughly 1.7% from September 2025, according to local MLS-based reports cited by Dawn Sells San Diego and SnapDwell (dawnsellssandiego.com, snapdwell.com). At the same time, closed sales dropped about 14% year over year, signaling fewer completed transactions and more cautious buyers.
The story changes when you separate single‑family homes from condos and townhomes:
Detached homes (single‑family): Median sale price around $1,079,000, up 5.8% year over year. Inventory is tighter, and these homes are selling faster—about 37 days on market, nearly 10% quicker than last year. Closed and pending sales are both down double digits, but sellers still have the upper hand due to limited supply (loveryrealestate.com).
Attached homes (condos & townhomes): Median price around $670,000, essentially flat—down about 0.2% year over year. Inventory here has grown roughly 5–6%, days on market have stretched to about 44 days, and sales are off about 14%, pointing to a softer, more buyer‑friendly segment.
Early October “rolling 30‑day” data (through mid‑October) shows the median sold price dipping slightly to around $915,000, with homes taking about 51 days to sell and a market score leaning toward buyers (about 33 out of 100 on a buyer–seller scale), according to PocketAgentPro. That suggests the market is no longer the frenzied seller’s arena of 2021–2022, even if prices remain high.
Slower sales mean buyers can negotiate more, especially on condos and townhomes.
Mortgage Rates in October 2026: High, but Shop Around
The biggest headwind in San Diego right now is borrowing costs. As of mid‑to‑late October 2026, most 30‑year fixed mortgage rates in the area sit between 7.3% and 7.5%, very close to the national average of about 7.4% reported by Freddie Mac (monitorbankrates.com, apnews.com). Some local lenders and credit unions do stand out: Safe 1 Credit Union, for example, has recently advertised a 30‑year fixed rate near 6.00% (about 6.085% APR), which is significantly lower than many big‑bank offers.
On the higher end, jumbo and specialty loans can climb above 9%, especially for borrowers with lower credit scores or smaller down payments. That spread—from roughly 6% to the high‑8s/9s—means your personal rate will depend heavily on your credit profile, loan size, and loan‑to‑value ratio, not just where you apply.
💡 Pro Tip: When comparing offers, focus on APR, not just the headline rate. APR factors in lender fees and can reveal which loan is truly cheaper over time.
What This Means for San Diego Buyers in October 2026
For buyers, this fall is a trade‑off: more negotiating room and slightly better selection, especially in condos and townhomes, but at the cost of higher monthly payments due to rates in the 7–8% range. Realtor.com and Axios both highlight mid‑October—specifically the week of October 11–17—as one of the best times of year to buy in San Diego, with listing prices typically several percentage points below seasonal peaks and more active inventory on the market (axios.com).
If you’re determined to purchase in 2026, consider:
Focusing on attached homes where prices are flatter and sellers are more flexible.
Getting quotes from multiple lenders and credit unions—the difference between 6.0% and 7.5% can mean hundreds of dollars per month.
Planning a potential refinance in the future if rates ease, while making sure the payment you lock in today is still comfortable.
Guidance for Sellers: Strategy Matters More Than Ever
Sellers of detached homes in San Diego are still in a relatively strong position: prices are up 5–6% year over year, inventory is tight, and well‑priced homes can move in just over a month. However, the pool of qualified buyers has shrunk as rates climbed, so overpricing is more likely to backfire than in past years. For condo and townhome sellers, where inventory is higher and days on market are longer, realistic pricing, strong staging, and small concessions (like closing cost credits or rate‑buydown contributions) can make the difference between lingering and selling.
Overall, October 2026 in San Diego is a market in transition: home sales are slower, mortgage rates are elevated, and leverage is shifting slightly toward buyers—especially in the attached segment—while detached homes remain resilient. Whether you’re buying or selling, grounding your decisions in current data and carefully comparing mortgage options will help you navigate this moment with confidence.
A Little More Perspective on Today's Housing Market
Sandra, I've included three short videos that help explain some of the economic factors influencing today's real estate market. My intention isn't to overwhelm you with news, but to provide some helpful perspective on why the market is changing and what that means for buyers and sellers.
1. Housing Affordability — Why Buyers Are Being Priced Out
Watch Video: Housing Market Trends & Affordability
An overview of the affordability challenges facing today's homebuyers, including how the rising costs of homeownership are limiting the number of people able to purchase a home.
2. Why Home Sales Are Slowing
Watch Video: What's Behind the Slowdown in Home Sales?
A look at how inflation, mortgage interest rates, and the rising cost of living are affecting buyers' purchasing power and contributing to slower home sales.
3. Mortgage Interest Rates — Why They Matter So Much
Watch Video: Understanding Mortgage Rates and Their Impact
A helpful explanation of how mortgage rates influence monthly payments, buying power, and ultimately what buyers can afford to pay for a home.
My Perspective
These broader market trends are important to understand, but real estate is ultimately local. Your home's value will depend on comparable sales in your neighborhood, its condition, and the buyers actively shopping in your price range.
My job is to help you separate the headlines from the realities of your particular market, so you can make decisions based on facts rather than fear or speculation. I will provide you with a FREE Equity Report on your home, all I need is your address, name & email. No sales pitches, no heavy follow up - just good info and answer to your questions. I works by referral, not sales pressure.😉~ Thomas J Nelson
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/65ed25120013ad8189925cc4.jpeg
#58BB47
#0000FF
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/663e5366699c7e1eb628841a.jpeg
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph
Thank you for visiting
San Diego
Contact Info
Address
8895 Towne Centre Dr. Ste 105 PMB 436, San Diego, CA 92122-5542
Phone
+18582328722
Location
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph