There's So Much Happening Here
Welcome to
San Diego Neighborhood Experts
There's So Much Happening Here...
LOCAL AMBASSADOR
Thomas J. Nelson
Welcome, my friends, to San Diego Neighborhood Experts, your one-stop shop for all things local! Here, we bring you exclusive interviews with our beloved neighborhood businesses, the latest happenings in San Diego, fresh events to look out for, and of course, juicy tidbits about the ever-exciting real estate market. Stay classy, San Diego!
My mission is to inspire growth and cultivate financial freedom by delivering exceptional real estate services. As a perpetual learner and explorer, I serve others with energy and focus, using pragmatic communication and a global perspective to create deep connections and make a meaningful impact. A treasure hunter at heart, I embrace every opportunity to motivate and empower those I serve and achieve success in all our ventures.


San Diego Neighborhood Experts Podcast
Assumable Mortgages: Why Pay 7%+ When You Might Qualify for MUCH Less?
🏡 Assumable Mortgages: Why Pay 7%+
When You Might Qualify for MUCH Less?
What if you could buy a home today and take over the seller's existing mortgage at 3%, 3.5%, or even 4%, instead of today's higher interest rates?
It's possible! And it's called an ASSUMABLE MORTGAGE.
According to Freddie Mac, the average 30-year fixed mortgage rate was 7.40% as of October 8, 2026. Meanwhile, some homeowners are sitting on mortgages with interest rates dramatically lower than today's market.
Here's some basics on what buyers AND sellers should know!
🔑 Which Mortgages Are Assumable?
Three common government-backed mortgage programs offer assumptions
for qualified buyers:
VA Loans: Department of Veterans Affairs
FHA Loans: Federal Housing Administration
USDA Loans: U.S. Department of Agriculture
Most conventional mortgages are NOT assumable
under ordinary sale conditions.
But I'm Not a Veteran!
You don't have to be a Veteran to assume a VA loan!
Qualified civilian buyers can assume VA mortgages, subject to approval. However, the seller's VA loan entitlement may remain tied to that mortgage unless an eligible Veteran buyer substitutes their entitlement.
FHA and USDA assumptions also have eligibility and approval requirements.
💰 How Does an Assumable Mortgage Work?
Think of it as potentially combining two financing pieces:
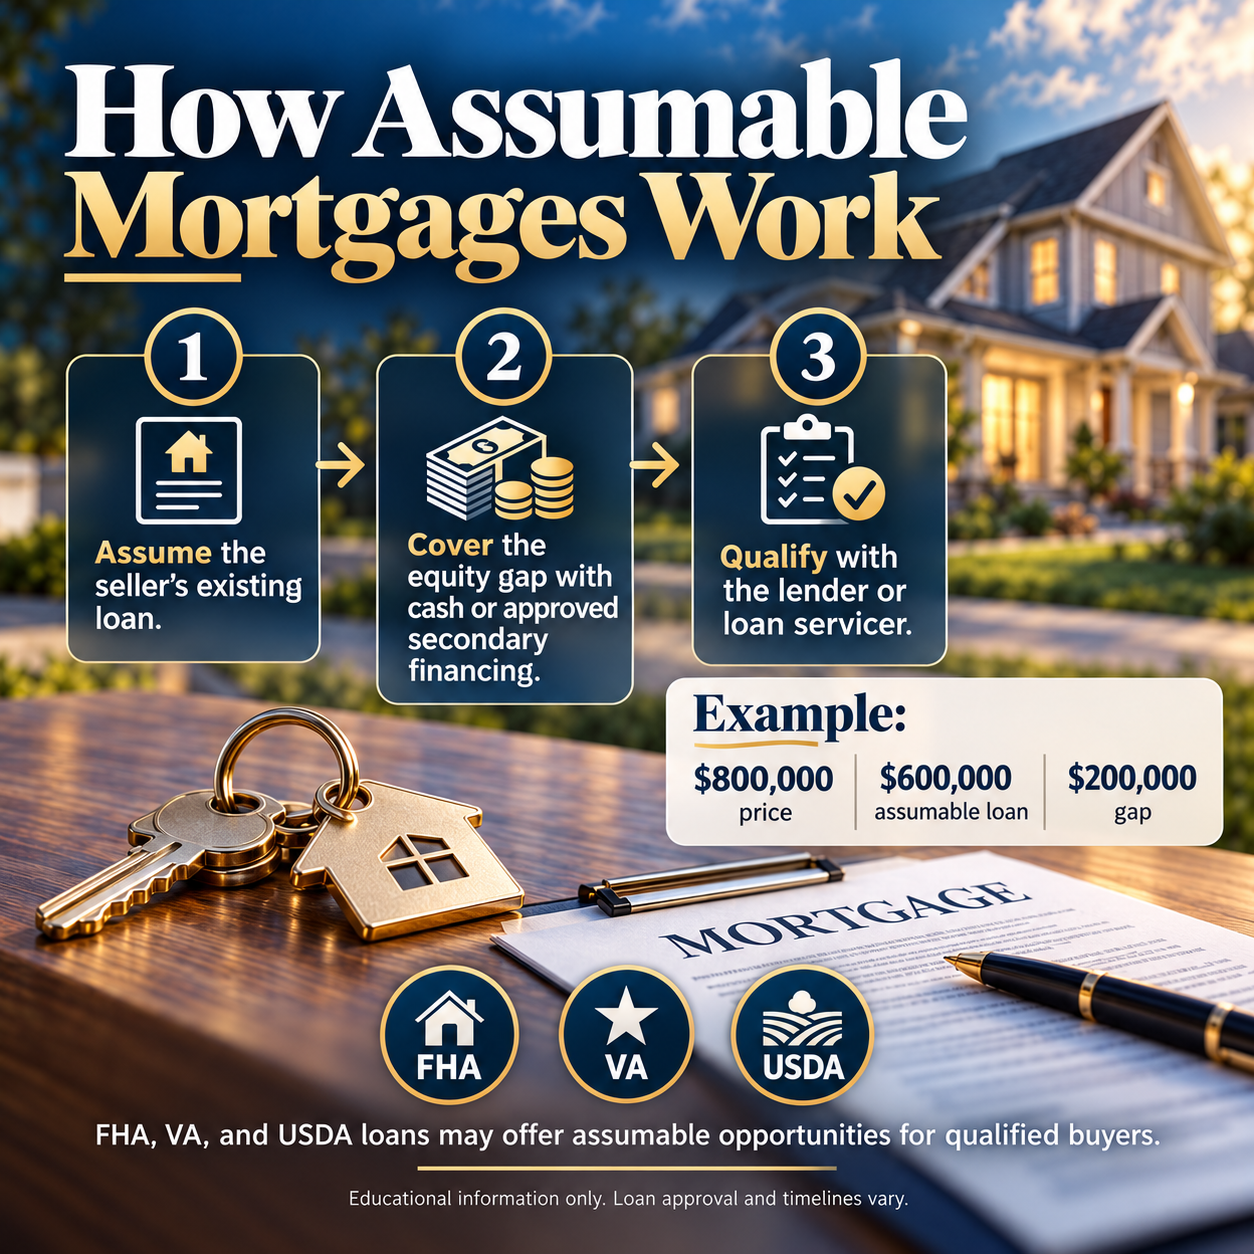
1. Primary Mortgage: You assume the seller's existing mortgage balance, interest rate, and remaining repayment terms.
2. The Equity Gap: You cover the difference between the home's purchase price and the remaining mortgage balance using cash or, when permitted, approved secondary financing.
Example:
🏠 Purchase Price: $800,000
🏦 Assumable Mortgage: $600,000 at 3.5%
💵 Equity Gap: $200,000
You would assume the existing $600,000 mortgage and cover the remaining $200,000 through cash, eligible secondary financing, or a combination.
If you have the cash, you don't need a second mortgage!
Keep in mind that secondary financing may carry a higher rate, and assumptions require approval and can take additional time.
🏡 SELLERS: Your Low Mortgage Rate Could Be a Marketing Advantage!
If you're selling a home with a low-interest VA, FHA, or USDA mortgage, don't overlook the opportunity to advertise its assumability!
In a competitive market, your existing mortgage could be a compelling reason for qualified buyers to consider your property.
The California Association of REALTORS® has even supported expanding assumable mortgages to improve housing affordability.
The bottom line? Before buying or selling, find out whether an assumable mortgage could create an opportunity worth exploring.
📞 Questions? Let's Talk! 858-232-8722
I'm a licensed REALTOR®, not a mortgage lender. This is general educational information, not lending or financial advice. Loan eligibility, assumptions, secondary financing, and approvals must be verified with the appropriate lender or servicer.
Helping buyers and sellers make informed real estate decisions since 1999.
🚨 Current Assumable Loan Property: 3.5% rate on over $600,000 of the purchase price!
Check It Out: 519 Heron Lane
My trusted lending partner can be a great potential resource with your assumable loan transaction:
Jason Gordon | Mortgage Lending
📱 619-200-8031
#ThomasJNelsonRealtor #SanDiegoNeighborhoodExperts #AssumableMortgage #VALoans #FHALoans #USDALoans #SanDiegoRealEstate #HomeBuying #MortgageRates #SanDiegoREALTOR

Assumable Mortgages: Why Pay 7%+ When You Might Qualify for MUCH Less?
🏡 Assumable Mortgages: Why Pay 7%+
When You Might Qualify for MUCH Less?
What if you could buy a home today and take over the seller's existing mortgage at 3%, 3.5%, or even 4%, instead of today's higher interest rates?
It's possible! And it's called an ASSUMABLE MORTGAGE.
According to Freddie Mac, the average 30-year fixed mortgage rate was 7.40% as of October 8, 2026. Meanwhile, some homeowners are sitting on mortgages with interest rates dramatically lower than today's market.
Here's some basics on what buyers AND sellers should know!
🔑 Which Mortgages Are Assumable?
Three common government-backed mortgage programs offer assumptions
for qualified buyers:
VA Loans: Department of Veterans Affairs
FHA Loans: Federal Housing Administration
USDA Loans: U.S. Department of Agriculture
Most conventional mortgages are NOT assumable
under ordinary sale conditions.
But I'm Not a Veteran!
You don't have to be a Veteran to assume a VA loan!
Qualified civilian buyers can assume VA mortgages, subject to approval. However, the seller's VA loan entitlement may remain tied to that mortgage unless an eligible Veteran buyer substitutes their entitlement.
FHA and USDA assumptions also have eligibility and approval requirements.
💰 How Does an Assumable Mortgage Work?
Think of it as potentially combining two financing pieces:
1. Primary Mortgage: You assume the seller's existing mortgage balance, interest rate, and remaining repayment terms.
2. The Equity Gap: You cover the difference between the home's purchase price and the remaining mortgage balance using cash or, when permitted, approved secondary financing.
Example:
🏠 Purchase Price: $800,000
🏦 Assumable Mortgage: $600,000 at 3.5%
💵 Equity Gap: $200,000
You would assume the existing $600,000 mortgage and cover the remaining $200,000 through cash, eligible secondary financing, or a combination.
If you have the cash, you don't need a second mortgage!
Keep in mind that secondary financing may carry a higher rate, and assumptions require approval and can take additional time.
🏡 SELLERS: Your Low Mortgage Rate Could Be a Marketing Advantage!
If you're selling a home with a low-interest VA, FHA, or USDA mortgage, don't overlook the opportunity to advertise its assumability!
In a competitive market, your existing mortgage could be a compelling reason for qualified buyers to consider your property.
The California Association of REALTORS® has even supported expanding assumable mortgages to improve housing affordability.
The bottom line? Before buying or selling, find out whether an assumable mortgage could create an opportunity worth exploring.
📞 Questions? Let's Talk! 858-232-8722
I'm a licensed REALTOR®, not a mortgage lender. This is general educational information, not lending or financial advice. Loan eligibility, assumptions, secondary financing, and approvals must be verified with the appropriate lender or servicer.
Helping buyers and sellers make informed real estate decisions since 1999.
🚨 Current Assumable Loan Property: 3.5% rate on over $600,000 of the purchase price!
Check It Out: 519 Heron Lane
My trusted lending partner can be a great potential resource with your assumable loan transaction:
Jason Gordon | Mortgage Lending
📱 619-200-8031
#ThomasJNelsonRealtor #SanDiegoNeighborhoodExperts #AssumableMortgage #VALoans #FHALoans #USDALoans #SanDiegoRealEstate #HomeBuying #MortgageRates #SanDiegoREALTOR
San Diego Neighborhood Experts is a FREE community initiative to help locals get to know each other and encourage everyone to shop local!
Apply to have your business interviewed and featured on the podcast for free!
San Diego Blogs
Assumable Mortgages: Why Pay 7%+ When You Might Qualify for MUCH Less?
🏡 Assumable Mortgages: Why Pay 7%+
When You Might Qualify for MUCH Less?
What if you could buy a home today and take over the seller's existing mortgage at 3%, 3.5%, or even 4%, instead of today's higher interest rates?
It's possible! And it's called an ASSUMABLE MORTGAGE.
According to Freddie Mac, the average 30-year fixed mortgage rate was 7.40% as of October 8, 2026. Meanwhile, some homeowners are sitting on mortgages with interest rates dramatically lower than today's market.
Here's some basics on what buyers AND sellers should know!
🔑 Which Mortgages Are Assumable?
Three common government-backed mortgage programs offer assumptions
for qualified buyers:
VA Loans: Department of Veterans Affairs
FHA Loans: Federal Housing Administration
USDA Loans: U.S. Department of Agriculture
Most conventional mortgages are NOT assumable
under ordinary sale conditions.
But I'm Not a Veteran!
You don't have to be a Veteran to assume a VA loan!
Qualified civilian buyers can assume VA mortgages, subject to approval. However, the seller's VA loan entitlement may remain tied to that mortgage unless an eligible Veteran buyer substitutes their entitlement.
FHA and USDA assumptions also have eligibility and approval requirements.
💰 How Does an Assumable Mortgage Work?
Think of it as potentially combining two financing pieces:
1. Primary Mortgage: You assume the seller's existing mortgage balance, interest rate, and remaining repayment terms.
2. The Equity Gap: You cover the difference between the home's purchase price and the remaining mortgage balance using cash or, when permitted, approved secondary financing.
Example:
🏠 Purchase Price: $800,000
🏦 Assumable Mortgage: $600,000 at 3.5%
💵 Equity Gap: $200,000
You would assume the existing $600,000 mortgage and cover the remaining $200,000 through cash, eligible secondary financing, or a combination.
If you have the cash, you don't need a second mortgage!
Keep in mind that secondary financing may carry a higher rate, and assumptions require approval and can take additional time.
🏡 SELLERS: Your Low Mortgage Rate Could Be a Marketing Advantage!
If you're selling a home with a low-interest VA, FHA, or USDA mortgage, don't overlook the opportunity to advertise its assumability!
In a competitive market, your existing mortgage could be a compelling reason for qualified buyers to consider your property.
The California Association of REALTORS® has even supported expanding assumable mortgages to improve housing affordability.
The bottom line? Before buying or selling, find out whether an assumable mortgage could create an opportunity worth exploring.
📞 Questions? Let's Talk! 858-232-8722
I'm a licensed REALTOR®, not a mortgage lender. This is general educational information, not lending or financial advice. Loan eligibility, assumptions, secondary financing, and approvals must be verified with the appropriate lender or servicer.
Helping buyers and sellers make informed real estate decisions since 1999.
🚨 Current Assumable Loan Property: 3.5% rate on over $600,000 of the purchase price!
Check It Out: 519 Heron Lane
My trusted lending partner can be a great potential resource with your assumable loan transaction:
Jason Gordon | Mortgage Lending
📱 619-200-8031
#ThomasJNelsonRealtor #SanDiegoNeighborhoodExperts #AssumableMortgage #VALoans #FHALoans #USDALoans #SanDiegoRealEstate #HomeBuying #MortgageRates #SanDiegoREALTOR
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/65ed25120013ad8189925cc4.jpeg
#58BB47
#0000FF
https://storage.googleapis.com/msgsndr/LGvMHSpjamZ678AUgrJY/media/663e5366699c7e1eb628841a.jpeg
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph
Thank you for visiting
San Diego
Contact Info
Address
8895 Towne Centre Dr. Ste 105 PMB 436, San Diego, CA 92122-5542
Phone
+18582328722
Location
https://www.google.com/maps/embed?pb=!1m18!1m12!1m3!1d429155.3376406009!2d-117.43861812897623!3d32.82469764779043!2m3!1f0!2f0!3f0!3m2!1i1024!2i768!4f13.1!3m3!1m2!1s0x80d9530fad921e4b%3A0xd3a21fdfd15df79!2sSan%20Diego%2C%20CA%2C%20USA!5e0!3m2!1sen!2sph!4v1710098235283!5m2!1sen!2sph